
14 min 04 sec
Available in: English
 ไทย
EnglishไทยI Will Teach You To Be Rich: No Guilt. No Excuses. Just a 6-Week Program That Works
By Ramit Sethi
A plain, practical plan to fix your credit, earn more on savings, open retirement accounts, invest through one simple fund and automate everything, so your money grows while you spend freely on what matters to you.
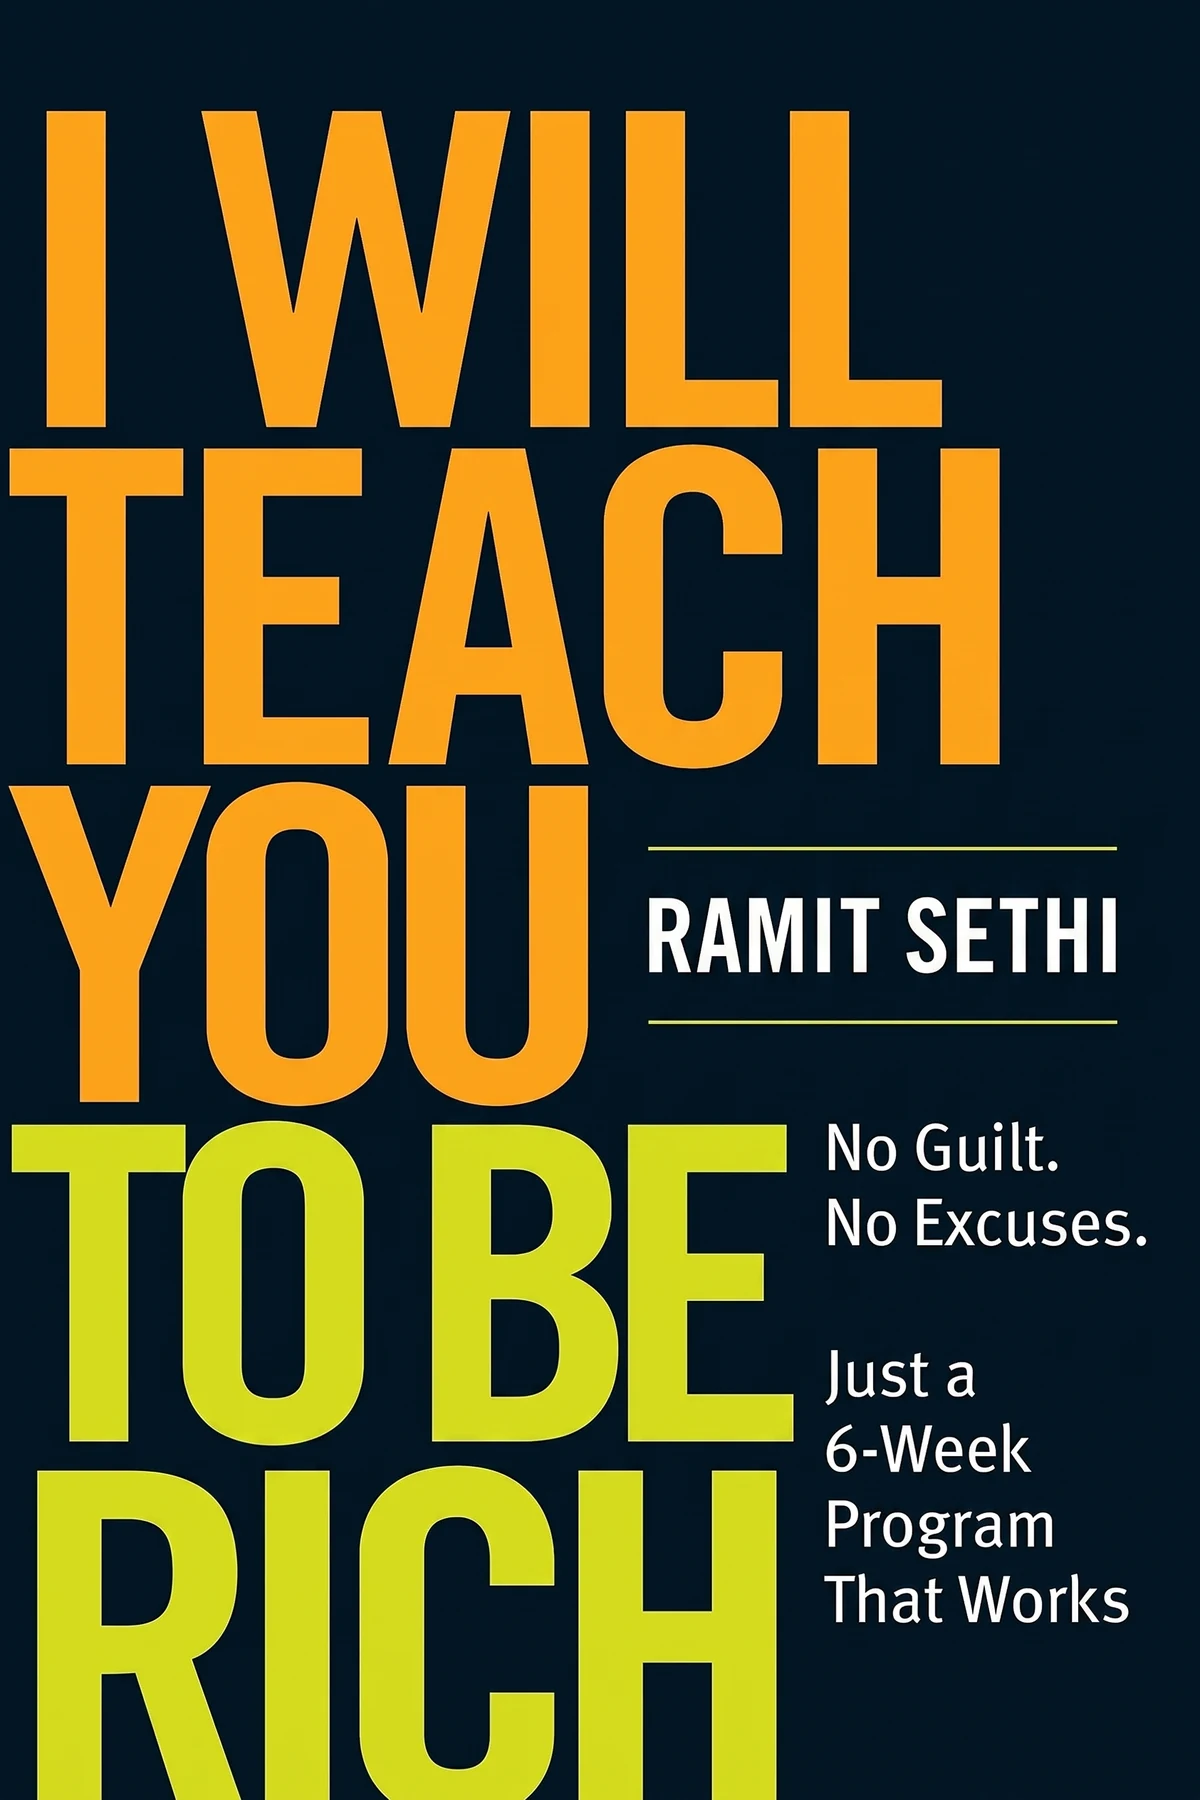
Table of Content
1. Introduction
53 sec
If money makes you feel guilty or behind, the fix may be smaller than you expect: a plan designed so you have to do almost nothing. That is the promise of I Will Teach You To Be Rich, by personal finance advisor and entrepreneur Ramit Sethi. He shows that a good credit score alone can cut about $70,000 from the cost of one home loan, simply through lower interest.
Sethi’s case is that wealth comes from a system you build once and then leave alone. It has a few parts: credit used well, bank accounts that pay you, retirement saving started early, a spending plan without guilt, and investing kept boring on purpose. Each part comes with figures you can hold against your own statements. The plan ends with money that saves and invests itself every month, while you spend freely on the things you actually care about.
2. Stop the excuses and start with a dollar
1 min 35 sec
Most people who never save have a reason ready, and it usually sounds reasonable. The 2008 crash shows what those excuses can cost, and the amount you start with matters less than starting, since even $1 a day adds up.
3. Spend freely on what you love, cut the rest
1 min 44 sec
A friend gets a raise and moves somewhere smaller. It sounds backward, until you see the rule behind it, one that turns budgeting from a punishment into permission to spend.
4. Turn your credit card into a money saver
1 min 52 sec
Two people buy the same house with the same loan, and one pays tens of thousands of dollars more. The difference is a single number most people rarely check.
5. Earn six to ten times more on savings
1 min 41 sec
Fees and near-zero interest feel like the normal price of having a bank. They aren’t. A simple comparison shows how much a sleepy account costs you every year you leave it alone.
6. Open retirement accounts even with fifty dollars
1 min 46 sec
A student could not scrape together the money to open an investment account, and it looked like she would have to wait years. She found another way in: an account with no minimum and an automatic $50 a month.
7. Skip the stock pickers and own one simple fund
1 min 51 sec
Professional advisers sound certain about which shares to buy. One piece of research found how often they kept backing companies that were about to collapse, and the alternative Sethi offers asks almost nothing of you.
8. Set up money that moves itself every month
1 min 33 sec
Bills, savings and investments can all happen in the first week of the month without you lifting a finger. The schedule is simple, and one mid-month check keeps it honest.
9. Conclusion
1 min 09 sec
Sethi’s program adds up to a trade. You give about six weeks to setting up credit, accounts and transfers, and in return you get years of not thinking much about money. The guilt that keeps people from starting turns out to be beside the point, because the plan was never built on being good every day. It rests on getting the defaults right.
That is why the 20 percent of guilt-free spending matters as much as the 10 percent invested. Sethi wants people to choose their own splurges and ignore anyone who tells them what is acceptable. If rare sneakers matter more to you than a weekly restaurant meal, eat out less and buy the shoes.
The same thinking guides windfalls. When a bonus, a gift or a raise arrives, Sethi suggests saving half and spending the other half however you like, so your lifestyle never quietly outgrows your income. A good place to begin is one phone call this week asking your card company for lower fees, or one online savings account opened tonight.
Jim gave up floor space to spend more nights camping. Rich, in Sethi’s sense, means money that runs by itself and goes where you care.
About this book
What is this book about?
Many people feel guilty or behind about money. They tell themselves it is too late, that nobody taught them, or that they cannot spare enough to make a difference. Ramit Sethi argues that none of this holds up. Saving and investing are simple once the right accounts exist and the money moves on its own. His plan is built so you do as little as possible. He shows how a strong credit score can save about $70,000 on a single mortgage, and why online banks can pay six to ten times more interest. He explains how two US retirement accounts, the 401(k) and the Roth IRA, work together. His Conscious Spending Plan sets aside money for investing and saving first and leaves 20 percent to spend without guilt. For investing, he skips stock tips in favor of one age-based fund. Readers get a step-by-step setup, from calling a card company for lower fees to a monthly schedule of automatic transfers. Once it runs, it keeps saving and investing whether they think about it or not.
Book Information
Who it's for
Guilty about money
Young professionals who feel guilty about money and want a setup that saves and invests without daily effort.
Graduates
Graduates with card debt or idle cash in a low-interest bank account.
Employees unsure about retirement
Employees unsure how workplace retirement plans, personal retirement accounts and simple index or age-based funds fit together.
About the Author
Ramit Sethi
Ramit Sethi is an American author, entrepreneur and personal finance advisor who writes and speaks publicly about money. I Will Teach You To Be Rich, first published in 2009, became a New York Times bestseller. He hosts a podcast with the same name and hosted the 2023 Netflix series How to Get Rich. He studied technology and psychology at Stanford, co-founded the wiki company PBworks and also wrote Money for Couples.
Ratings & Reviews
Ratings at a glance
What people think
Listeners find this personal finance guide highly accessible and value the transparent, sequential directions, particularly highlighting the uncomplicated technique for establishing an automated framework. This book delivers solid basic concepts and useful pointers, assisting them in mastering their money matters and earning hundreds of dollars. They appreciate the direct style that sidesteps technical jargon, making it an effective and swift experience.
Top reviews
Rosa
Finally got around to reading this classic, and I’m kicking myself for not starting it five years ago. This book completely strips away the confusing jargon that usually makes financial planning feel like a foreign language. The step-by-step instructions for setting up an automated system are worth the price of the book alone. I followed the advice on negotiating my bank fees and saved a couple hundred dollars in one afternoon. It’s incredibly practical because it focuses on big wins rather than obsessing over three-dollar sandwiches. The tone is irreverent and punchy, which keeps the subject matter from becoming a total snore-fest. Personally, I found the investment chapters to be the most enlightening part of the whole experience. It gives you enough knowledge to be dangerous without needing a degree in economics. This is the financial manual they should have handed us at high school graduation.
Show morePongpan
As someone who has always been terrified of the stock market, this book was a complete game-changer for my anxiety. Ramit doesn't just talk about numbers; he focuses on the philosophy of a 'Rich Life,' which is deeply personal. I stopped feeling guilty about my travel spending once I automated my savings and retirement contributions. The instructions are so clear that you could probably set everything up while half-asleep on a Sunday afternoon. I’ve already seen a massive shift in my net worth just by following the 'Ladder of Personal Finance.' It feels like having a big brother who is a genius with money giving you the straight talk you need. No more wondering where my paycheck went at the end of every single month. This book empowers you to take charge of your financial situation without requiring you to become a spreadsheet nerd.
Show moreTom
The chapter on credit cards alone justifies the time spent reading this cover to cover. I had no idea how much power I actually had to negotiate my interest rates or get annual fees waived just by asking. Ramit provides actual scripts to use with customer service representatives, which takes all the guesswork out of the process. It’s rare to find a book that offers such immediate, tangible ROI within the first few chapters. The focus on automation is a stroke of genius for lazy people like me who hate manual budgeting. I’m finally building a 'Rich Life' that includes guilt-free spending on things I actually love, like high-quality tech. The writing style is fast-paced and avoids the dry, academic tone of most finance books. You don’t need to be an expert to follow his 6-week program and see results. Essential reading for everyone.
Show moreMalee
Ever wonder why some people always seem to have money for vacations while you’re struggling to pay rent? This book explains the system behind that freedom without making you feel like a failure. It’s a practical handbook that focuses on earning hundreds of dollars through big wins like salary negotiation and proper investing. I followed the advice on automation, and now my bills pay themselves before I even see the money. It’s such a relief to not have to think about my finances on a daily basis anymore. The 'Conscious Spending Plan' is much more realistic than a traditional, restrictive budget that no one ever follows. Ramit encourages you to spend extravagantly on the things you love, which is a message you don't hear often. This book gave me the tools to stop being cheap and start being frugal. It’s the ultimate guide for taking back control.
Show morePloy
Frankly, the automated system described in this book is the only reason I have any savings at all today. I used to be the person who would spend everything in my checking account and hope for the best. Setting up the automatic transfers between my accounts took less than an hour, and it has changed everything. I love that Ramit doesn't judge you for your spending habits as long as you're hitting your investment goals. The book is incredibly straightforward and avoids the fluff that usually fills up personal finance guides. It’s a fast read, but the impact is long-lasting if you actually do the work he suggests. My credit score has already started to climb thanks to the tips in the first chapter. If you’re tired of feeling guilty about money, this is the book you need to read right now.
Show moreValentina
Picked this up during a quarter-life crisis, and it actually provided the roadmap I desperately needed. The 6-week action plan makes the overwhelming world of finance feel like a series of small, manageable chores. I love the concept of 'conscious spending'—the idea that I can buy my expensive lattes if I cut back elsewhere is refreshing. Truth is, Ramit’s voice can be a bit much; he definitely leans into that 'bro-ey' persona that might rub some the wrong way. However, if you can ignore the cringey jokes about hot blondes, the actual mechanics of the advice are bulletproof. Automating my accounts has already saved me hours of stress every month. It’s not just about being cheap; it’s about making your money work for the life you actually want to live. Definitely a solid foundational read for anyone who feels paralyzed by their bank account.
Show moreBoss
Look, I was skeptical about the clickbaity title, but the content inside is surprisingly high-quality and actionable. The main takeaway for me was the 85% solution—realizing that getting started is more important than being perfect. I spent years paralyzed by choice, not knowing which index fund was the absolute best one to pick. Ramit’s straightforward approach helped me just pick a target-date fund and move on with my life. My only real gripe is that he occasionally sounds like he’s trying too hard to be the 'cool' financial guru. Some of the jokes land flat and feel a bit dated in today’s social climate. Regardless, the foundational knowledge he provides regarding 401(k) matches and Roth IRAs is indispensable for beginners. It’s a very quick read because there isn’t any confusing jargon to slow you down.
Show moreEarn
After hearing about this book for years, I finally dove in and I'm impressed by the clarity of the instructions. The step-by-step nature of the 6-week plan is perfect for someone who usually gets bored by financial talk. It’s very easy to understand, even if you’ve never opened a brokerage account in your entire life. I did find the profanity and the 'frat boy' humor a bit unnecessary and distracting at times. In my experience, the best parts of the book are when he focuses on the psychology of money rather than just the math. He really hammers home the point that you don't need to be a financial expert to get rich. The advice on 'beating the banks' is particularly satisfying and led to an immediate win for me. It’s a solid foundational text, though I would pair it with something more modern for tax specifics.
Show morePooja
To be fair, the financial advice here is exceptionally sound, but the delivery is just so polarizing. Ramit Sethi has this 'fratboy' persona that feels incredibly dated, especially with the constant references to gender stereotypes. It’s a 3-star experience for me because I spent half the time rolling my eyes at his arrogance. If you can push past the grating personality, the chapters on index funds and Roth IRAs are gold. He explains the difference between various accounts in a way that actually makes sense for a beginner. Not gonna lie, the 85% solution is a great psychological trick to get people to just start moving. I still think there are better-written versions of this information available now without the unnecessary snark. It’s a decent starting point if you have a thick skin and a high tolerance for bad jokes.
Show moreArthit
Not what I expected given the hype, mostly because the target audience seems to be 22-year-olds living in 2009. The advice is extremely basic—common sense things like 'pay off your credit cards' and 'don't pay bank fees.' Frankly, if you’ve spent five minutes on a personal finance subreddit, you’ve already seen everything this book has to offer. The narration style is also incredibly distracting; it’s filled with weirdly aggressive side comments that feel out of place in a professional guide. I struggled to get through the audiobook because the tone was just so patronizing and juvenile. It lacks the depth needed for anyone who is already mid-career or has a more complex financial life. It might save you some time to just look up a summary online instead of wading through the filler. Wish I had skipped this one.
Show moreQuestions about this book
What is the main idea of I Will Teach You To Be Rich?
Ramit Sethi argues that saving and investing are simple once you build the right system. Use credit wisely, keep money in no-fee, high-interest accounts, open retirement accounts early, invest through one simple fund and automate every transfer. His Conscious Spending Plan puts money into investing and saving first, then leaves about 20 percent to spend without guilt, so the system keeps working whether or not you think about it.
What is the Conscious Spending Plan?
It is Sethi’s way of budgeting without guilt. He suggests about 60 percent of income for fixed costs such as rent and debt, 10 percent for investments, 10 percent for savings goals and 20 percent for guilt-free spending. The idea is to cut hard on things you don’t value and spend freely on things you do, like his friend Jim, who chose a smaller apartment so he could camp more.
What is the difference between a 401(k) and a Roth IRA in the book?
Both are US retirement accounts. A 401(k) is offered through an employer, takes money before tax and may include matching money from the company, but withdrawals are taxed in retirement. A Roth IRA is opened with your own money after tax, lets you choose investments like stocks or index funds, and its growth and retirement withdrawals are tax-free. Sethi strongly recommends having both.
How does Ramit Sethi say you should invest?
He advises ignoring expert stock picks, because no one can reliably predict the market. He cites research described by Daniel Solin in which 47 of 50 advisory firms kept recommending companies until they went bankrupt. Instead, he favors lifecycle, or age-based, funds that adjust their mix automatically. A Vanguard Target Retirement fund, for example, holds 90 percent stocks for a 25-year-old and shifts toward bonds with age.
How do you automate your finances according to the book?
Sethi’s Automatic Money Flow links every account on a schedule. If you are paid on the first, money goes to your 401(k) and checking on the second, to savings and your Roth IRA on the fifth, and bills and the credit card are paid on the seventh. He also suggests keeping a $1,000 cushion in checking and a mid-month reminder to compare spending with your plan.
Readers also enjoyed

AUDIO SUMMARY AVAILABLE
Listen to I Will Teach You To Be Rich in 15 minutes
Get the key ideas from I Will Teach You To Be Rich by Ramit Sethi, plus 5,000+ more nonfiction titles.
- 5,000+ titles
- Listen as much as you want
- 7-day free trial
- Cancel anytime









