
14 min 43 sec
Available in: English
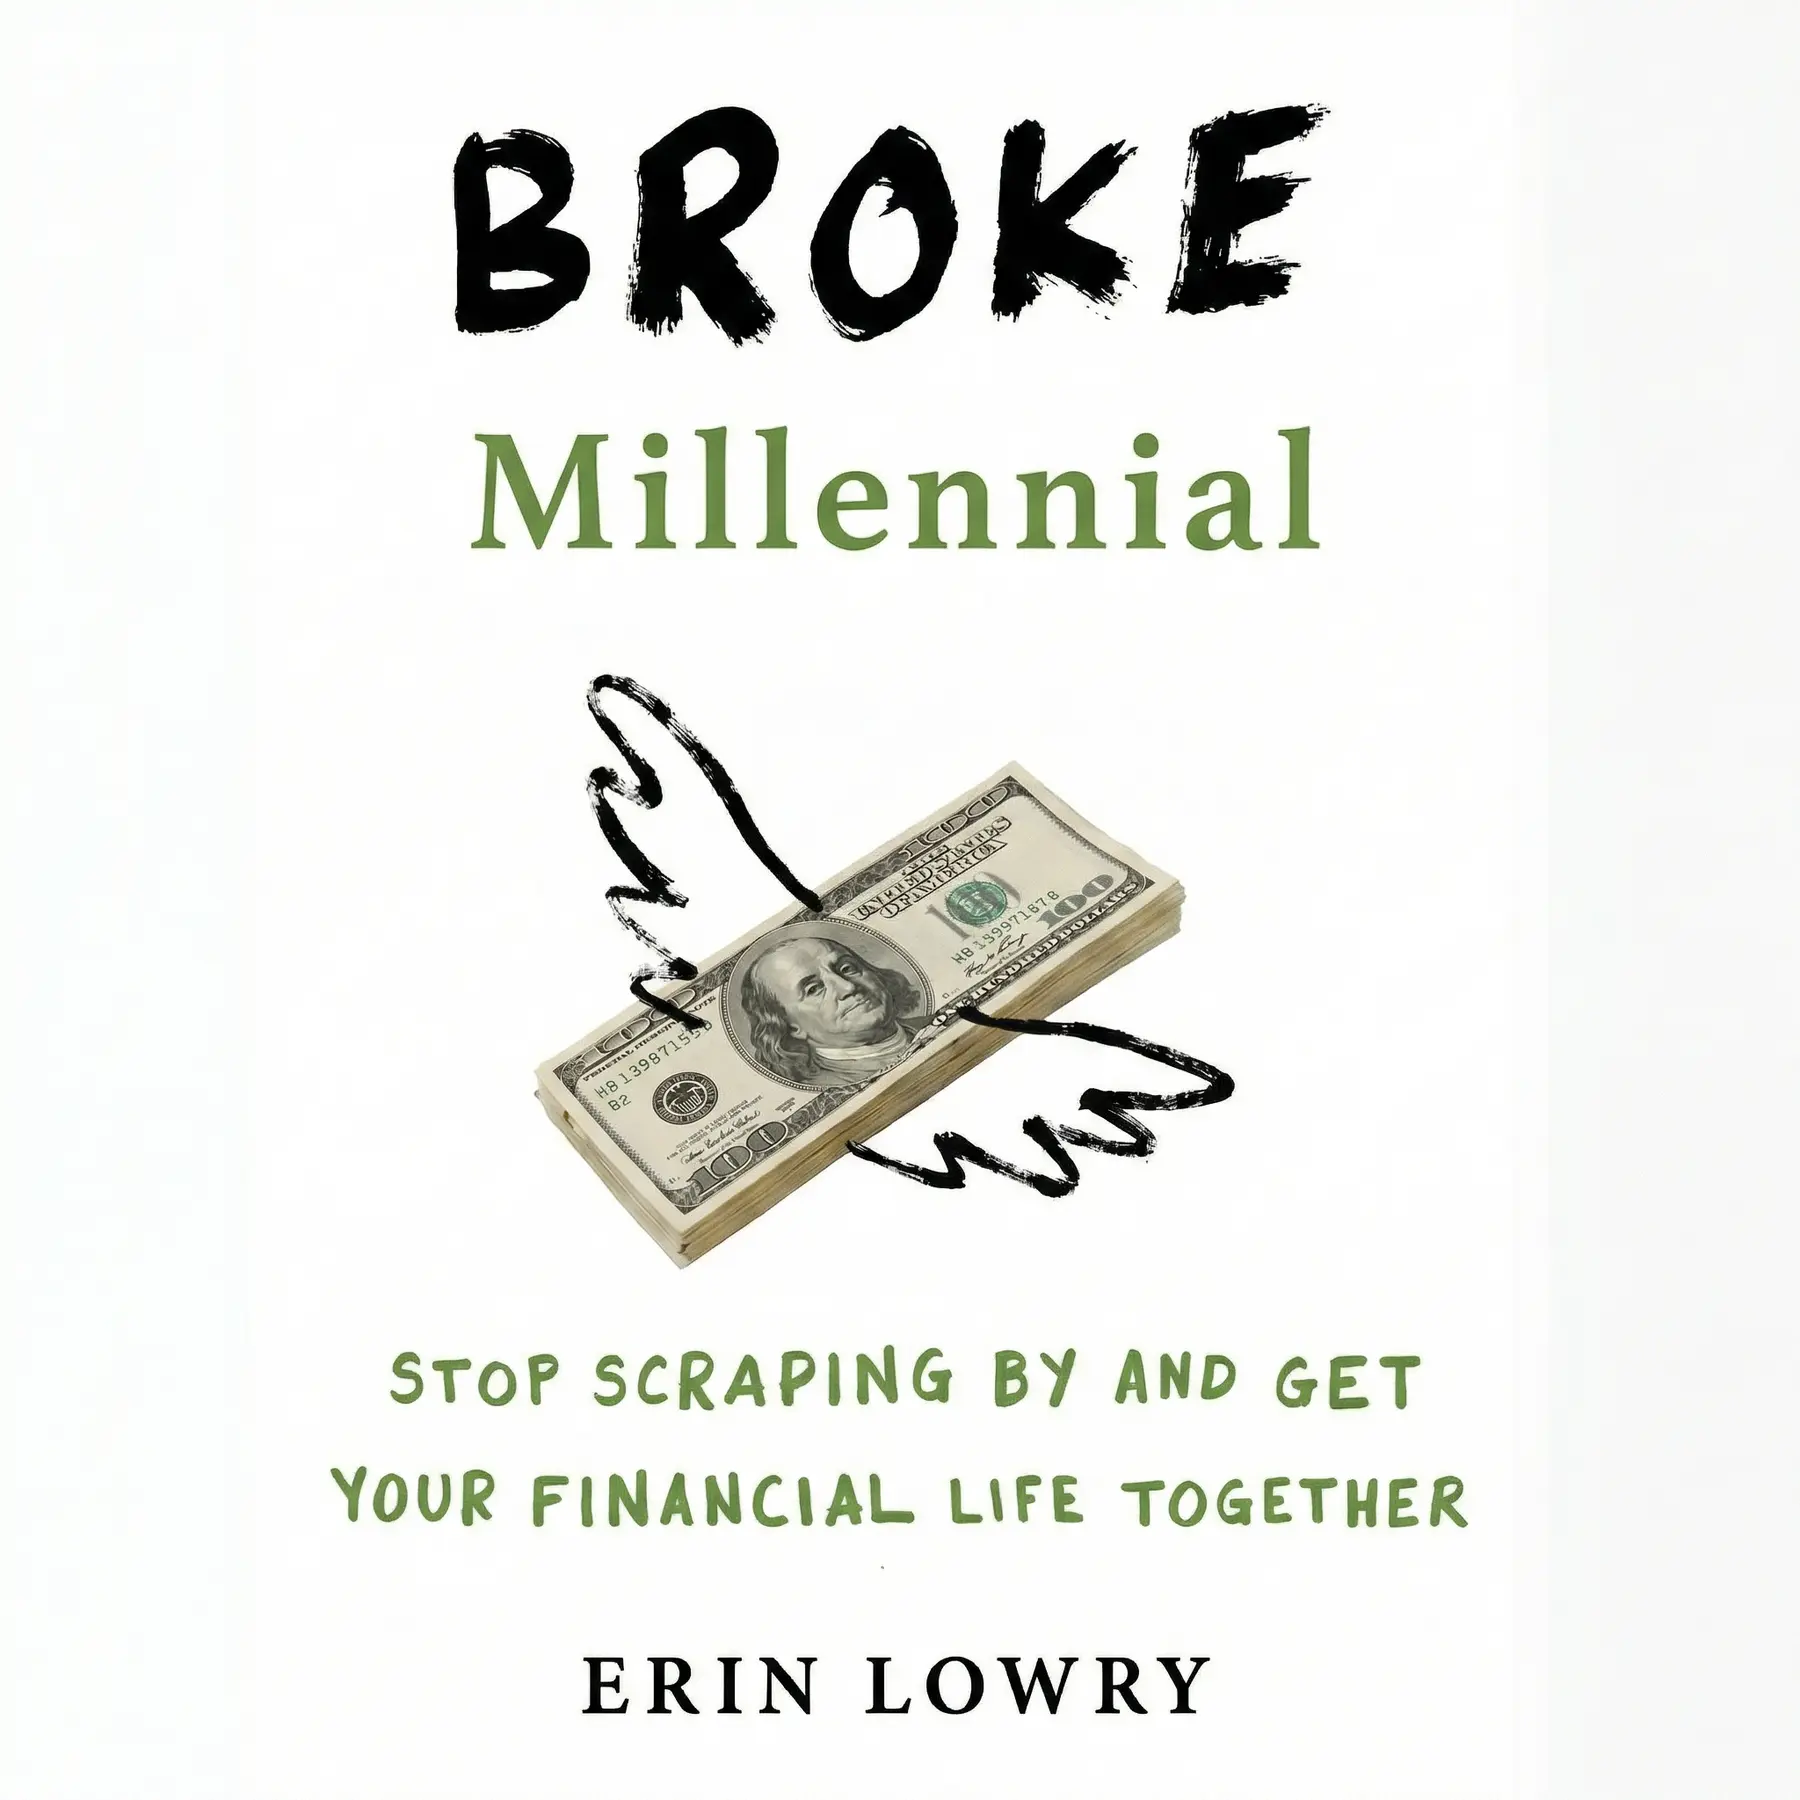
Broke Millennial: Stop Scraping By and Get Your Financial Life Together
By Erin Lowry
A plain, practical guide for young adults who find money stressful: how to see where your habits come from, choose a budget that fits you, avoid card debt and build a safety cushion.
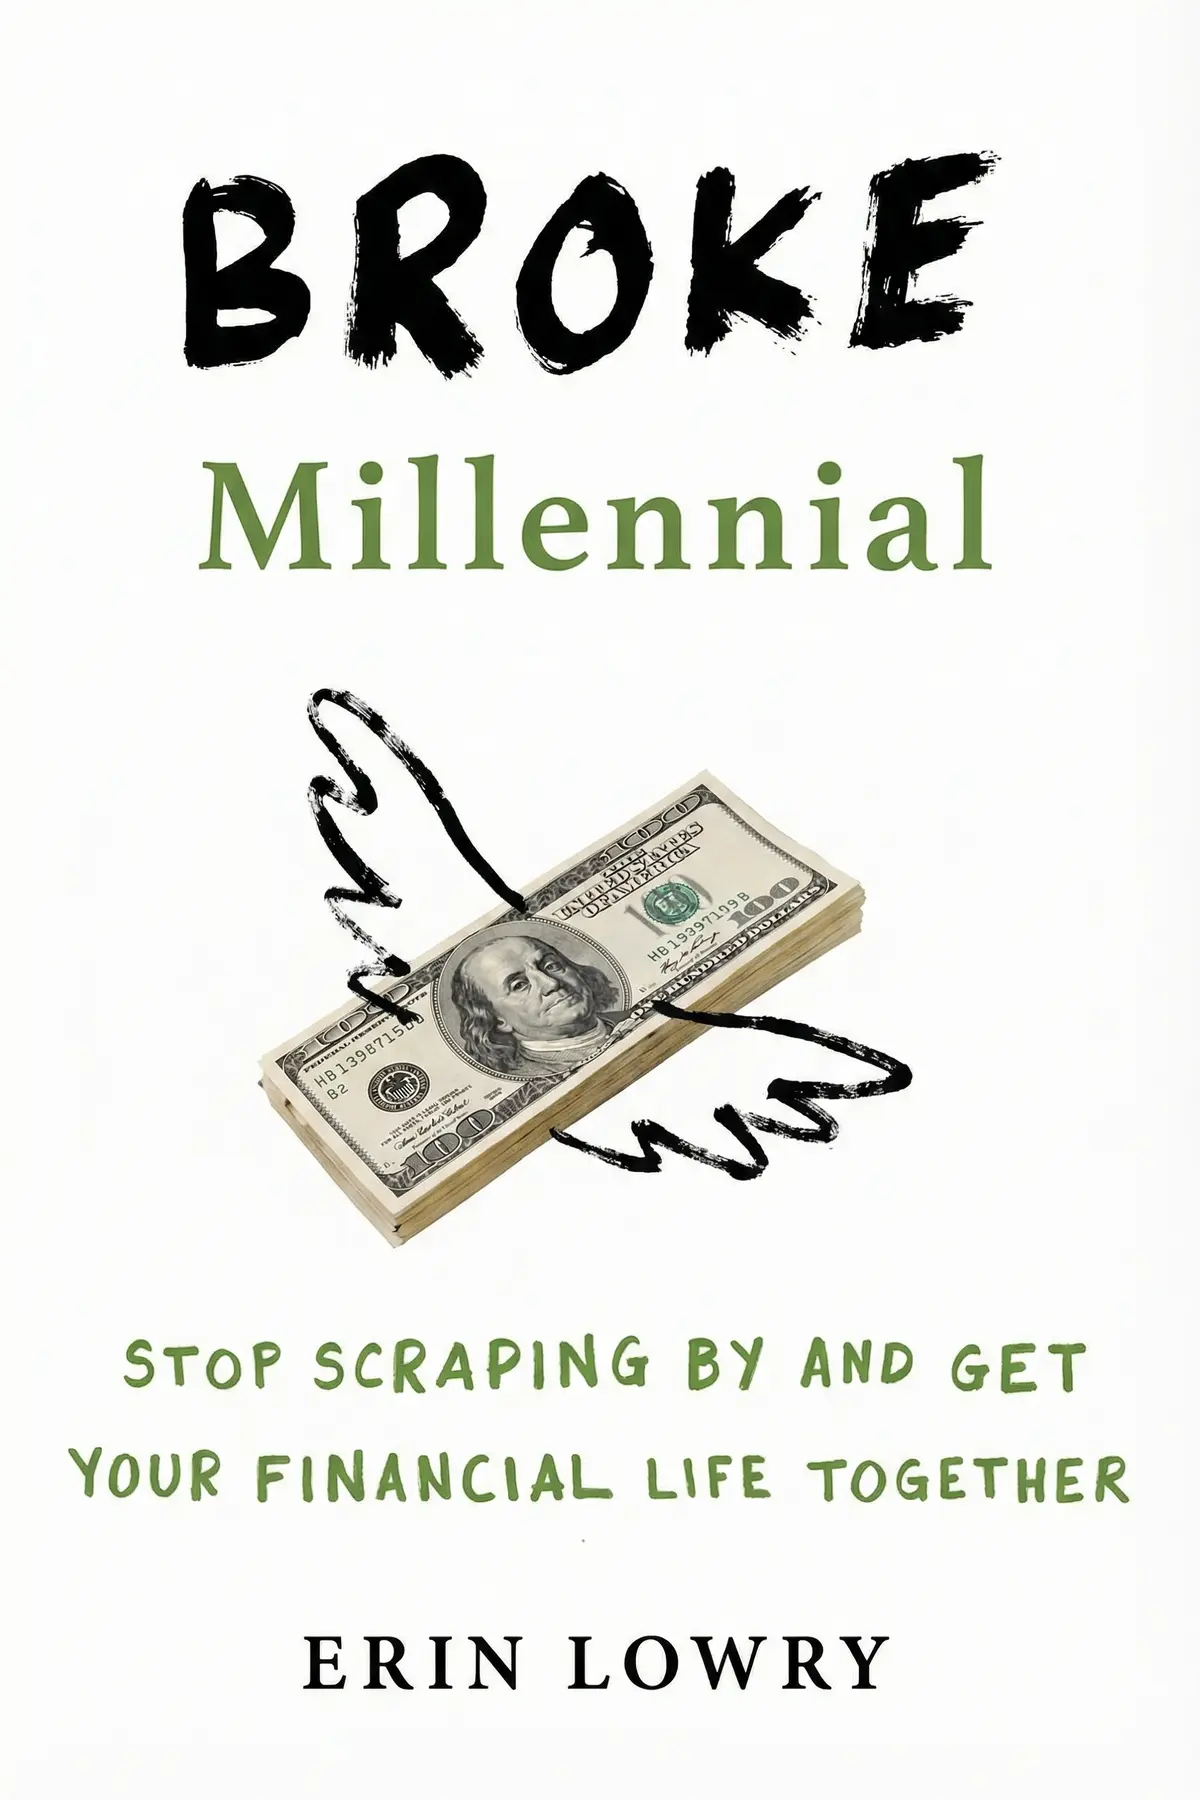
Table of Content
1. Introduction
59 sec
If paying rent already feels like a stretch, saving for emergencies or retirement can seem out of reach. In Broke Millennial, personal finance author Erin Lowry argues that the distance between scraping by and being in control is crossed in small, specific moves, starting with something as modest as setting aside ten dollars from every paycheck.
She writes for people in their twenties and early thirties who find money confusing and frightening, and she believes that fear is what keeps them stuck. No complex formulas are needed. What helps is understanding where your money habits come from, then stacking up a few practical steps until the stress loses its grip.
Those steps run from honest questions about childhood to a budget that suits your temperament, a bank that actually pays you, one firm rule for credit cards and an emergency fund sized to your real life. Each is small enough to begin before your next payday.
2. Trace your money habits back to childhood
2 min 03 sec
A bright, debt-free 23-year-old stayed in a job she disliked for one reason she could barely explain. Lowry traces that kind of paralysis to a place most people never think to look.
3. Choose the budget style that fits your weakness
1 min 43 sec
One budgeting method asks you to go back to paper money; the other asks you to record every cent. Which one works depends on a question about yourself most budgets never ask.
4. Split your pay into three realistic shares
2 min 01 sec
The textbook rule for dividing a paycheck sounds sensible until rent swallows half of it. A fictional New Yorker named Dwight shows what to do when the ideal numbers simply don’t fit.
5. Make your savings earn real interest online
1 min 45 sec
Your bank lends out your deposits and earns handsomely on them. What it pays you in return may not cover two minutes in a laundromat dryer, and switching takes one search.
6. Use credit cards without paying their interest
1 min 39 sec
Every card statement shows two numbers, and the smaller one is the dangerous one. Lowry explains how that figure lures millions into debt, and the single habit that keeps a card working for you.
7. Pay yourself first, starting with ten dollars
1 min 45 sec
Waiting to save whatever is left at month’s end almost guarantees nothing is left. Lowry’s alternative starts with skipping a single cocktail, and it ends with a habit you no longer have to think about.
8. An emergency fund sized to your real life
1 min 36 sec
Six months of expenses is the classic advice, but it fits some people and crushes others. Lowry sets different targets for the indebted, the debt-free and the self-employed.
9. Conclusion
1 min 12 sec
Lizzie’s problem was never intelligence. She had no system, so money stayed a fog she preferred not to look into. Lowry’s book turns that fog into a set of decisions, each modest enough to make in an afternoon, and each one making the next easier. Knowing why you overspend tells you which budget to try. The budget frees the ten dollars you pay yourself. A better bank helps that money grow, and a fund of the right size keeps a bad month away from your credit card.
The same steadiness carries into social life. Lowry describes a familiar dinner: you order the cheapest dish and one drink while friends keep adding rounds and appetizers, and an even split leaves you paying $80 for ordinary tacos and a lemonade. You can hold your ground and risk being called cheap, or offer to divide the bill yourself, since most groups gladly hand that dull job to a volunteer.
This week, look at your balance instead of hoping, set up one small automatic transfer to savings and check what your bank pays you. Control over money rarely comes from one big decision. It comes from small ones you stop putting off.
About this book
What is this book about?
Many people in their twenties and early thirties are smart, employed and still afraid to open their banking app. Erin Lowry argues that this fear holds them back from the lives they want, and that it rarely comes from a lack of ability. Most of them simply never learned how money works, and their habits were formed in childhood long before the first student loan or credit card. Lowry's approach is to replace dread with a series of small, specific steps. She starts with honest questions about your earliest memories of money, then offers two very different budgeting styles, a realistic way to divide your pay into shares, and a case for moving savings to an online bank that pays real interest. She explains exactly how credit card bills are built to trap people, why paying yourself first matters even when you barely break even, and how big your emergency fund should be depending on your debt, dependents and work. Readers get a clear, unhurried method that starts with as little as ten dollars a paycheck and grows from there.
Book Information
Who it's for
Avoiding their bank balance
Graduates and young professionals who avoid checking their bank balance and hope the money lasts.
City renters wanting budgets
City renters whose rent eats half their pay and who want a budget that fits reality.
Wanting savings despite debt
Anyone carrying card or student debt who wants a first, small savings habit and a safety cushion.
About the Author
Erin Lowry
Erin Lowry has written two books on personal finance, Broke Millennial and Broke Millennial Takes On Investing, and MarketWatch named her first book one of the top money books of 2017. Her writing has appeared in Fast Company, Cosmopolitan and Refinery29, and she has appeared on CBS Sunday Morning and CNBC. She speaks at universities and conferences, spent most of her childhood in Asia and now lives in New York City.
Ratings & Reviews
Ratings at a glance
What people think
Listeners describe this financial guide as educational and accessible, highlighting its actionable tips and entertaining wit. It acts as an excellent starting point for managing finances, improving clarity on monetary matters, and makes for a perfect present for younger audiences. Listeners value the way it's written—with one specifically mentioning its conversational tone—and consider the content highly relatable and a good investment.
Top reviews
Kasemsan
Finally got around to reading this after seeing Erin on The Financial Diet, and it’s exactly the wake-up call I needed. I’ve always been terrified of my bank account, but this book made me feel like I could actually take control without needing a degree in finance. The way she breaks down the 'debt wreckage' into manageable steps is brilliant. I especially appreciated the bulleted summaries at the end of each chapter because they make it so easy to go back and reference specific points later. It truly felt like chatting with a knowledgeable friend over coffee rather than sitting through a boring lecture. Truth is, I’ve already recommended this to three of my coworkers who are also living paycheck to paycheck. It’s funny, approachable, and doesn't make you feel stupid for not knowing what a 401k is. This is hands down the best introductory guide for my generation.
Show moreNannapat
Wow, where was this book when I was a freshman in college? I’ve spent years trying to figure out budgeting through trial and error, but this guide puts everything in one place. It covers all the things school and my parents never mentioned, like how to handle money in a relationship or how to negotiate a salary. The layout is great, and the humor actually made me laugh out loud a few times. Personally, I didn't find the tone smug at all; it felt realistic and urgent. If you’re someone who feels behind the curve, this will give you the confidence to start moving forward. The advice isn't about deprivation, but about being smart so you can actually afford the things you care about. It’s informative, fun, and totally worth the price of admission for any young adult.
Show moreJeeranan
Personally, I loved the bulleted summaries at the end of every section because they helped me retain the information. I’ve read a lot of finance blogs, but having all this info consolidated into 18 clear chapters was a game changer. The book covers everything from debt wreckage to the basics of investing without ever becoming dry or boring. I didn't feel bored once, which is rare for this genre. It’s an incredibly informative guide that doesn't just tell you what to do, but explains the 'why' behind it. I’ve already recommended it to my younger cousins who are about to graduate. The conversational tone made me feel like I wasn't alone in my struggles. It’s an easy-to-maneuver guide that genuinely helps remove the stress surrounding your bank account. Highly recommended for anyone in their 20s!
Show moreRiley
After hearing a few podcast interviews with Erin Lowry, I decided this would be the perfect graduation gift for my younger sister. I ended up reading it myself first and was pleasantly surprised by how much I actually learned about brokerage accounts. The author has a knack for taking intimidating topics and stripping away the jargon. Not gonna lie, some of the 'millennial lingo' is a bit much, but the core advice on tackling student loans and building an emergency fund is rock solid. It’s a lighthearted take on a stressful subject. I liked that the book encourages you to skip around to the chapters that actually apply to your current situation rather than forcing a linear read. While it lacks some of the deep-dive technicality a finance pro might want, it’s an essential primer for anyone who feels overwhelmed by their wallet.
Show moreParichat
The chapter on credit scores alone was worth the cover price for me. Before reading this, I had no idea how my different accounts were impacting my rating, and Lowry explains it without being condescending. I love that I can pick this up and just read the sections on investing or retirement without feeling lost. Got to say, the writing style is very punchy and keeps you engaged, which is a miracle for a book about money. My only real gripe is that it feels very New York-centric. Not everyone is worried about the cost of brunch or big-city rent, and sometimes those examples felt a bit repetitive. Despite that, the practical steps for getting out of debt are universal. It’s a great resource that removes the shame often associated with being 'broke' and replaces it with a clear, actionable plan.
Show moreTantipat
Look, if you’re looking for a dense, academic textbook on global economics, keep moving. This book is for the person living paycheck to paycheck who needs a roadmap out of the woods. Erin Lowry manages to make personal finance feel less like a chore and more like a challenge you can actually win. In my experience, most finance books are written for people who already have money to invest, so it was refreshing to read something for those of us just trying to survive. The advice is realistic, even if the author's own background seems a bit more privileged than the average reader's. I found the 'cutesy' style easy to read during my commute. It’s a solid four stars for being an accessible, helpful, and non-intimidating entry point into adulthood. It really helped me stop burying my head in the sand about my debt.
Show moreNora
Ever wonder why they don't teach this stuff in high school? I’m a 'Zillennial' and found this book to be a lifesaver for navigating my first real job. It helps you handle those awkward money conversations with friends that always come up during dinner or trips. A bit heavy on the 'start by 25' pressure, though, which I could see being a turn-off for some. Not gonna lie, I skipped a few chapters that didn't apply to me yet, but that’s the beauty of the structure. The author is very direct, and while she can be a bit blunt, I think that’s what our generation needs. It’s a practical, funny, and well-organized resource for anyone trying to get their act together. It might be basic for some, but for me, it was the perfect starting point.
Show moreSue
This book is a bit of a mixed bag for me. On one hand, the conversational tone makes it incredibly easy to digest in just a couple of sittings. On the other hand, I think I’m just a few years too old for the target demographic. As an 'older millennial,' the heavy use of hashtags and Tinder metaphors like 'swiping left' on bad spending habits felt a little forced and will likely age poorly. My experience was that the advice is fantastic for a 22-year-old just starting out, but if you’re already in your 30s, the constant refrain that you should have started at 20 makes you feel a bit hopeless. There were some great resources regarding credit scores and navigating awkward money talks with friends, which I found useful. However, the heavy focus on urban socialite problems didn't always resonate with my lifestyle. It’s a solid gift for a college grad, though.
Show moreChiw
As someone who already has a decent handle on their 401k, I found the advice a little too entry-level for my needs. It is definitely a nice introduction to money topics, but it lacks the depth I was hoping for regarding Vanguard accounts or specific investment strategies. To be fair, the author admits it’s a 'basics' book, so I can't be too mad. The 'swipe left' terminology and constant hashtagging felt a bit like she was trying too hard to be 'relatable' to kids. I also noticed the 'start early or you’re screwed' sentiment that others have mentioned, which can be a bit discouraging if you're over 25. That said, the section on navigating financial conversations with parents was actually quite insightful. It’s a well-written book, just make sure you know it's truly for beginners before you buy it.
Show moreTuck
To be fair, I went into this with high expectations since I follow the author’s blog, but the tone really rubbed me the wrong way. Frankly, it felt like being lectured by a younger sibling who has never actually experienced a financial crisis. Most of the advice seems predicated on having parents who already set you up for success, which makes the 'pull yourself up by your bootstraps' vibe feel incredibly hollow. I found her approach to student debt almost patronizing, as if those of us struggling just didn't try hard enough to avoid it. If you aren't living a high-flying, big-city lifestyle with bottomless mimosas, a lot of these anecdotes will feel alienating. While the writing is cutesy and fast-paced, the constant 'do this or you are screwed' messaging is more anxiety-inducing than helpful. It’s a well-organized book, but the smugness overshadowed the actual utility of the information for me.
Show moreQuestions about this book
What is Broke Millennial by Erin Lowry about?
It is a practical personal finance guide for people in their twenties and early thirties who find money stressful and confusing. Lowry argues that this fear holds people back, and that small steps fix it: understanding the childhood roots of your money habits, choosing a budget style that suits you, moving savings to a higher-interest online bank, paying credit cards in full, paying yourself first and building an emergency fund.
What budgeting methods does Broke Millennial recommend?
Lowry offers two. The cash diet moves spending from cards to cash, since research she cites shows people spend less with cash, and she suggests weekly amounts plus a $100 buffer. Track every penny logs each purchase in a spreadsheet to reveal hidden patterns, like the friend who found she spent nearly $100 a month on bottled water. She also suggests working toward a 50, 20 and 30 split of take-home pay.
How big should an emergency fund be according to Erin Lowry?
It depends on your situation. If you carry heavy debt or are underemployed, aim for at least $1,000 for one person, plus at least $500 per dependent, including pets. If you are debt-free or your debt is manageable, save six months of essential expenses. Freelancers should aim for nine months. Keep it as cash in an account paying at least 1 percent, not in stocks.
How do you pay yourself first when you barely break even?
Lowry suggests starting tiny. Skip one $10 cocktail or two $5 coffees each pay period and move that money to savings. Once that feels normal, raise it to $20, $50 or $100. Then automate it by asking your employer to send the amount directly to savings each payday, or by setting up an automatic transfer at your bank, so you never have to decide again.
Does Broke Millennial say to avoid credit cards?
No. Lowry says cards help build the credit score you will need to borrow later, for example for a house. The rule is to charge only what you can repay and to pay the full balance every month. Paying just the minimum triggers interest that can reach 20 percent a year or more, a trap she says pulls millions into growing debt.
Featured in
Readers also enjoyed

Big Mistakes: The Best Investors and Their Worst Investments
Michael Batnick

Buffett: The Making of an American Capitalist
Roger Lowenstein
AUDIO SUMMARY AVAILABLE
Listen to Broke Millennial in 15 minutes
Get the key ideas from Broke Millennial by Erin Lowry, plus 5,000+ more nonfiction titles.
- 5,000+ titles
- Listen as much as you want
- 7-day free trial
- Cancel anytime









