Rich Dad’s Increase Your Financial IQ: Get Smarter with Your Money
Robert T. Kiyosaki
 English
 ไทย
Shows why a salary alone rarely builds wealth and how to grow it instead: telling assets from liabilities, building holdings beside your job, learning how money and tax work, and taking informed risks.
55 sec
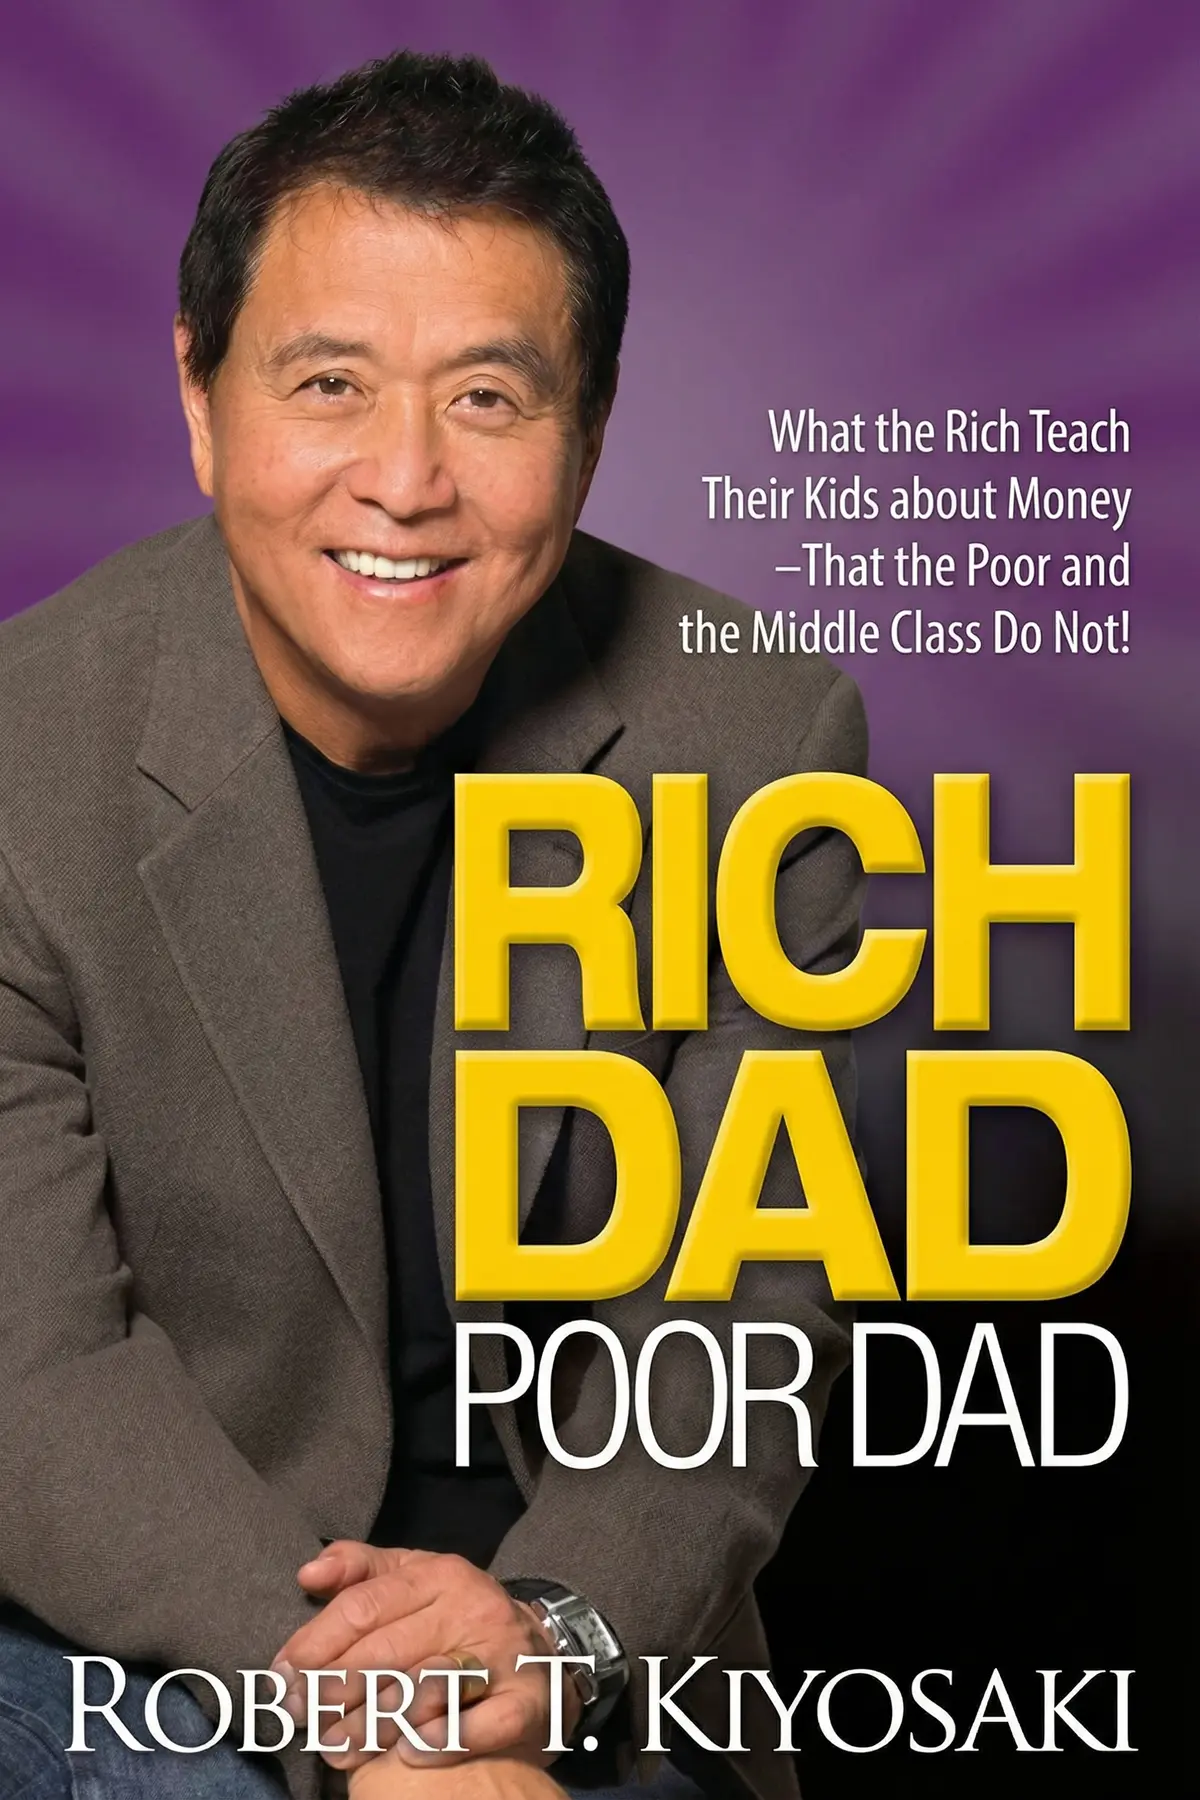
Working harder for a bigger salary feels like the road to wealth, yet Robert Kiyosaki argues it mostly enriches other people: your employer, your lenders and the tax office. In Rich Dad, Poor Dad, he sets the advice of two fathers side by side. His own father, a highly educated man, urged him to stay in school and land a secure job. His best friend’s father, a business owner who never finished the eighth grade, taught him to buy things that put money into his pocket.
Kiyosaki builds his whole case on that second lesson. Wealth, in his view, grows from owning assets that earn for you, and from the knowledge and nerve it takes to collect them, while a paycheck mainly covers the bills. Along the way come a blunt test for what counts as an asset, a way to build holdings without quitting your job, a look at why tax rules favor business owners, and a fresh way to choose your next job.
1 min 34 sec
A nine-year-old agreed to work for a few cents an hour in exchange for lessons about money. Weeks later he was furious and ready to quit, and that anger turned out to be the first lesson.
1 min 43 sec
Most people believe they already own their biggest asset. Rich dad’s simple definition suggests many of them own their biggest drain instead, and it gives you a test to apply before every large purchase.
1 min 32 sec
Telling people to stop chasing a salary sounds easy until the rent is due. Kiyosaki’s answer starts with a comic book rental run by a nine-year-old and a distinction most employees never make.
1 min 36 sec
A favorite childhood hero struck rich dad as nothing more than a crook. His reasons reveal how business owners and employees face very different rules on taxes and on what they stand to lose.
1 min 41 sec
Years of classes rarely include a single lesson on saving, investing or interest. Kiyosaki shows what that gap costs adults with good degrees, and how a car bought four years late proves the fix.
1 min 46 sec
Plenty of smart, careful people stay financially stuck while bolder ones pull ahead. Kiyosaki traces the difference to one missing ingredient, and a single interest rate comparison shows what playing safe can cost.
1 min 27 sec
Six months into a secure, well-paid job, a young graduate walked away to learn to fly. One father was baffled and the other congratulated him, and their split shows how to judge any job offer.
1 min 06 sec
This advice is said to have laid the groundwork for the fortune he went on to build, an estimated net worth of about one hundred million dollars, and his two fathers make the argument easy to carry around. Both men worked hard. Both were intelligent. One had a doctorate that never did much for his income; the other left school early and grew rich. What separated them was where their money and hours went: to bills, or to things that earned.
That frame works on an ordinary week. Look at your largest monthly payment and judge it by rich dad’s test of whether it adds to your wallet or drains it. Write down where you stand, what you can truly afford and one goal worth waiting for, the way Kim waited four years and let the apartment buildings pay for her car. Give some of your time to a business of your own, and pick your next job partly for what it will teach you.
The nine-year-old who stormed back over 10 cents an hour thought he had been cheated. He had just been handed the lesson that shaped his life: a wage pays you once, and an asset keeps paying.
Most people are raised on one piece of money advice: study hard and find a secure job. Robert Kiyosaki argues that this keeps people working for bosses, lenders and the tax office while their own wealth barely grows. He makes his case through two father figures. His own father was highly educated but earned modestly. His friend Mike's father was a business owner who never finished the eighth grade, grew rich and mentored both boys. The lessons Kiyosaki takes from that mentor are simple to state and hard to unlearn. The rich, he says, do not work for money. They buy assets that put money into their pockets, avoid liabilities that drain it, build a business of their own beside their job, use corporations to their advantage, and take risks backed by knowledge. Readers get a plain test for every large purchase, a three-step way to start a financial education at any age, and a new way to judge job offers: by what they teach, as well as what they pay.
Young earners deciding what to do with their first salaries and wondering why raises never feel like progress.
Employees who want to build income on the side without quitting a secure job.
Anyone raised on study hard, get a good job who never learned about assets, taxes or investing.
Robert T. Kiyosaki was born in 1947 in Hilo, Hawaii. After college in New York he served as a Marine Corps officer and helicopter gunship pilot in Vietnam, then sold for Xerox. In 1977 he launched a company selling nylon and Velcro surfer wallets, and in 1985 he founded an international company teaching business and investing. He sold it in 1994, retired at 47, created the board game CASHFLOW 101 and wrote Rich Dad, Poor Dad during that retirement. He later founded the Rich Dad Company, which teaches money skills through books and videos.
Robert T. Kiyosaki
Robert T. Kiyosaki
Robert T. Kiyosaki
Listeners find the material very straightforward and value the advice given, with one listener noting that it is appropriate for people of all ages. Additionally, the content prioritizes financial literacy and teaches people to think creatively, with one listener remarking that it serves as a helpful overview for people. Listeners also appreciate how the author clarifies difficult fiscal topics and aids in choosing better investments, all while delivering a novel approach to managing money.
Wow. This book fundamentally shifted how I perceive my bank account and my future. Kiyosaki’s central argument about the difference between assets and liabilities is incredibly simple yet profoundly disruptive for anyone stuck in the 9-to-5 grind. I spent years thinking my car was an asset, only to realize it was draining my pocket every single month. To be fair, the writing style is quite repetitive, and he drones on about his 'Rich Dad' without giving much concrete evidence that the man existed. However, the psychological impact is what matters here. It encourages you to stop being a 'loser' who works for money and start making money work for you. If you can get past the tough-love tone, there is real wisdom in these pages for people of all ages. It is a must-read for anyone wanting to escape the rat race once and for all.
Show moreFinally got around to reading this classic, and I wish I had picked it up ten years ago. It’s not just about money; it’s about the philosophy of work and the way our schools fail to prepare us for the real world. The book explains how we are programmed to be good employees rather than creators of wealth. I loved the section on 'mind your own business,' which emphasizes building your asset column while you keep your day job. Some critics say it’s too simple, but honestly, that’s why it works. It takes intimidating topics like taxes and corporations and makes them accessible to the average person. While the author's ego definitely shines through in certain chapters, the core lessons on financial self-reliance are invaluable. It has completely changed the way I look at my monthly expenses and long-term goals.
Show moreEver wonder why they don't teach money in school? This book answers that question by showing how the traditional education system is designed to produce employees, not employers. Rich Dad Poor Dad is a wake-up call for anyone who feels stuck in a cycle of earning and spending. I found the stories about his childhood adventures in business quite charming, even if they are a bit exaggerated. The book emphasizes that financial intelligence is more important than a high salary, which is a lesson everyone needs to hear. Personally, I think this should be mandatory reading for every high school senior. It encourages you to take calculated risks and stop letting fear dictate your financial future. While the writing isn't exactly high literature, the message is powerful enough to outweigh the clunky prose.
Show moreFrankly, this changed how I view my paycheck every two weeks. I used to see my salary as the limit of my wealth, but now I see it as a tool to purchase assets. Kiyosaki’s ability to explain the 'game' of money is unparalleled, making it feel like something anyone can master if they have the right mindset. He challenges you to think outside the box and question the traditional path of high debt and long hours. I appreciate the emphasis on accounting and understanding the law, as these are the tools the rich use to stay ahead. Sure, he's a bit repetitive and the dialogue feels fake, but the core principles of financial literacy are game-changers. This book gave me the 'why' that I was missing from other more technical financial guides. It’s a fantastic overview for anyone ready to take control of their life.
Show morePicked this up on a friend's recommendation after years of avoiding the hype. It’s a fast read, which is a blessing because the author tends to repeat himself every three chapters to drive a point home. The core message is powerful: focus on income-generating assets rather than just working for a salary. I appreciated how he breaks down complex financial concepts into stories that even a teenager could understand. Look, it’s not a technical manual on real estate or stocks, so don't expect a step-by-step guide to millions. Instead, think of it as a mental reset. I did find his dismissal of formal education a bit extreme and frankly irresponsible for certain professions. Not everyone can be an entrepreneur, and the world still needs doctors and engineers. Still, the perspective on 'paying yourself first' is something I'll be implementing immediately.
Show moreAs someone who has spent two decades in the corporate world, reading this felt like a punch to the gut. Kiyosaki describes the 'rat race' with such accuracy that it made me re-evaluate every financial decision I've made since college. The contrast between his highly educated but struggling 'Poor Dad' and his entrepreneurial 'Rich Dad' provides a compelling narrative framework. While the dialogue feels a bit stiff and staged, the underlying principles of financial literacy are solid. I especially liked the diagrams showing the flow of money; they made the abstract concepts of cash flow much more tangible. My only gripe is that he glosses over the risks of the investments he suggests. Real estate isn't always a sure bet, especially when the market saturates or bubbles burst. Overall, it’s a great overview for beginners who need to start thinking outside the traditional employment box.
Show moreThe chapter on assets versus liabilities alone is worth the price of the book. I’ve always been intimidated by finance, but Kiyosaki’s conversational tone made the subject feel approachable. He focuses heavily on the idea that the rich don't work for money—they make money work for them. It’s a radical shift for anyone raised with the 'get a good job' mentality. To be fair, the book is a bit dated, and some of the real estate advice feels like it belongs in a pre-2008 world. He also has a habit of making everything sound much easier than it actually is in practice. However, the motivation it provides is undeniable. It pushed me to start researching index funds and looking into small business opportunities. It’s a solid starting point for a financial education, even if it’s a bit light on the math.
Show moreNot what I expected, but in a good way. I thought this would be a dry textbook about stocks, but it’s actually a compelling narrative about two father figures with completely different worldviews. One dad is a brilliant academic who is always broke, and the other is a high-school dropout who becomes a multi-millionaire. It’s a polarizing book, and I can see why some people find it offensive or anti-intellectual. Frankly, he is quite hard on the 'Poor Dad' character, which can be tough to read. But if you focus on the logic of building a portfolio of income-producing assets, the book is incredibly helpful. It simplifies the path to financial freedom without getting bogged down in jargon. It’s an easy, engaging read that leaves you feeling empowered to make better choices with your paycheck.
Show moreTruth is, I have mixed feelings about this one. On one hand, the idea that your house isn't an asset is a fascinating take that really makes you think about your expenses. On the other hand, the book is incredibly light on actual 'how-to' details. He tells you to buy real estate and build businesses, but he never explains the logistics or the legal hurdles involved in those ventures. It felt like reading a 200-page motivational speech rather than an investment guide. Also, the way he disparages the 'working poor' and those who value job security can feel quite condescending at times. In my experience, you need a balance of stability and risk. It's worth a read for the mindset shift, but you'll definitely need to supplement it with more technical books if you want to actually start investing.
Show moreIs it just me, or is this book basically just a long advertisement for the author's other products? I went in expecting a roadmap to wealth, but instead, I got vague anecdotes and a lot of repetitive 'tough love' storytelling. He claims that your home is a liability, which any accountant will tell you is technically incorrect from a balance sheet perspective, even if his logic about cash flow makes some sense. The lack of specifics is what really bothered me; he mentions turning $60,000 into $80,000 without explaining the mechanics of the deal. Not gonna lie, I felt a bit embarrassed reading this in public because it carries that 'get rich quick' vibe. It might get you excited about money, but the lack of verifiable facts makes me question the entire premise. If you want real advice, read something like 'The Millionaire Next Door' instead.
Show moreKiyosaki argues that working harder for a salary rarely makes anyone rich, because most of what you earn goes to bosses, lenders and taxes. The wealthy, he says, buy assets that put money into their pockets and reinvest the income. He tells the story through two father figures: his own educated father and his friend Mike’s father, a business owner who mentored him.
By rich dad’s definition, an asset adds money to your wallet and a liability removes it. A home bought with a 30-year mortgage means 360 monthly payments plus property taxes leaving your income. Kiyosaki also argues those payments could have gone into investments that paid you back, so in his view the house costs you twice.
No. Kiyosaki separates your profession, the work that pays the bills, from your business, the assets you build with your time and money. He worked long hours at Xerox and at Standard Oil of California while keeping expenses low and investing what was left. A salary, in his view, is what funds the assets that eventually make you rich.
Kiyosaki suggests three steps. Take an honest look at your income and the expenses you can carry, counting only money you have. Set realistic goals, as his wife Kim did when she waited four years for a car paid for by their apartment buildings. Then build your financial knowledge through classes, seminars, books and contact with experts, and choose jobs partly for what they teach.
It suits people raised on the advice to study hard and find a secure job who now wonder why their income never turns into wealth. Young earners deciding what to do with a first salary, employees who want a side business without quitting, and anyone who never learned about assets, taxes or investing at school will find its lessons direct and easy to apply.
AUDIO SUMMARY AVAILABLE
Get the key ideas from Rich Dad, Poor Dad by Robert T. Kiyosaki, plus 5,000+ more nonfiction titles.